Employee stock options can be a valuable part of a startup compensation package, but they are often misunderstood. An offer of 10,000 or 20,000 options may sound like immediate ownership, although the employee usually receives a contractual right to buy shares rather than shares themselves. The financial outcome depends on several factors, including the exercise price, the company's future value, tax obligations, and whether a buyer is eventually available. Understanding these conditions is essential before treating an option grant as part of personal wealth.
Within Cap Table and Startup Equity, employee stock options represent potential future ownership that can affect both employees and existing shareholders. Companies grant these rights to attract and retain talent, while employees accept the possibility of financial upside alongside meaningful uncertainty. An option grant can become valuable if the underlying shares appreciate, but it can also expire without producing a financial return.
This guide explains how employee stock options work, the difference between incentive and nonqualified options, and the costs involved in exercising them. It also examines what happens when an employee leaves a startup, how taxes can affect the outcome, and why private company stock options should be evaluated differently from ordinary salary.
Understanding Employee Stock Options
An employee stock option gives an individual the right, but not the obligation, to purchase a specified number of company shares at an agreed price. The price is generally established when the option is granted and is known as the exercise price or strike price.
For example, a company might grant an employee the right to purchase 10,000 common shares at $3 per share. If the employee later becomes entitled to exercise those options, purchasing all 10,000 shares would require $30,000. The employee does not automatically receive $30,000 in shares or cash merely because the grant has been approved.
The distinction between an option and an actual share is important. Before exercise, an option holder generally does not have the voting or dividend rights associated with the underlying shares. Those rights ordinarily arise after the shares are issued, subject to the company's governing documents and applicable restrictions.
Employees should also distinguish stock options from restricted stock units. An option usually requires payment of an exercise price, while an RSU generally represents a promise to deliver shares or another settlement once specified conditions are satisfied. The two arrangements can produce different tax and financial consequences.
How Employee Stock Options Work From Grant to Sale
The lifecycle of a stock option begins when the company approves an award under its equity incentive arrangements. The grant agreement identifies the number of options, exercise price, award type, applicable conditions, and expiration terms. Employees should receive sufficient documentation to understand the rights they are being offered.
The employee must then satisfy any conditions governing exercise. Many startup options become exercisable progressively as the employee completes qualifying service, although some companies permit earlier exercise. The governing documents determine exactly when the employee can purchase the underlying shares.
Exercising an option means using the contractual right to acquire shares. Depending on the company and transaction, this may require payment of the exercise price, applicable taxes, and other costs. The company then issues or transfers the relevant shares according to the award terms.
The final financial outcome usually depends on a later opportunity to sell the shares. For employees at private startups, this may occur through an acquisition, an approved secondary transaction, a public listing, or another permitted liquidity event. A successful exercise does not itself guarantee that the employee can immediately recover the money spent.
Incentive Stock Options and Nonqualified Stock Options
In the United States, two common forms of employee stock options are incentive stock options and nonqualified stock options. They provide similar contractual opportunities to acquire company shares, but the eligibility requirements and federal tax treatment can differ substantially.
Incentive stock options, commonly called ISOs, must satisfy specific requirements under Section 422 of the Internal Revenue Code. These options are generally available only to qualifying employees of the issuing corporation or certain related corporations.
Nonqualified stock options, commonly called NSOs, do not qualify for the special statutory tax treatment available to ISOs. Depending on the equity plan, they may be granted to employees and eligible nonemployee service providers, including certain advisers and consultants.
The following table compares the main differences under general US federal tax rules. Actual treatment depends on the grant documents, individual circumstances, and applicable law.
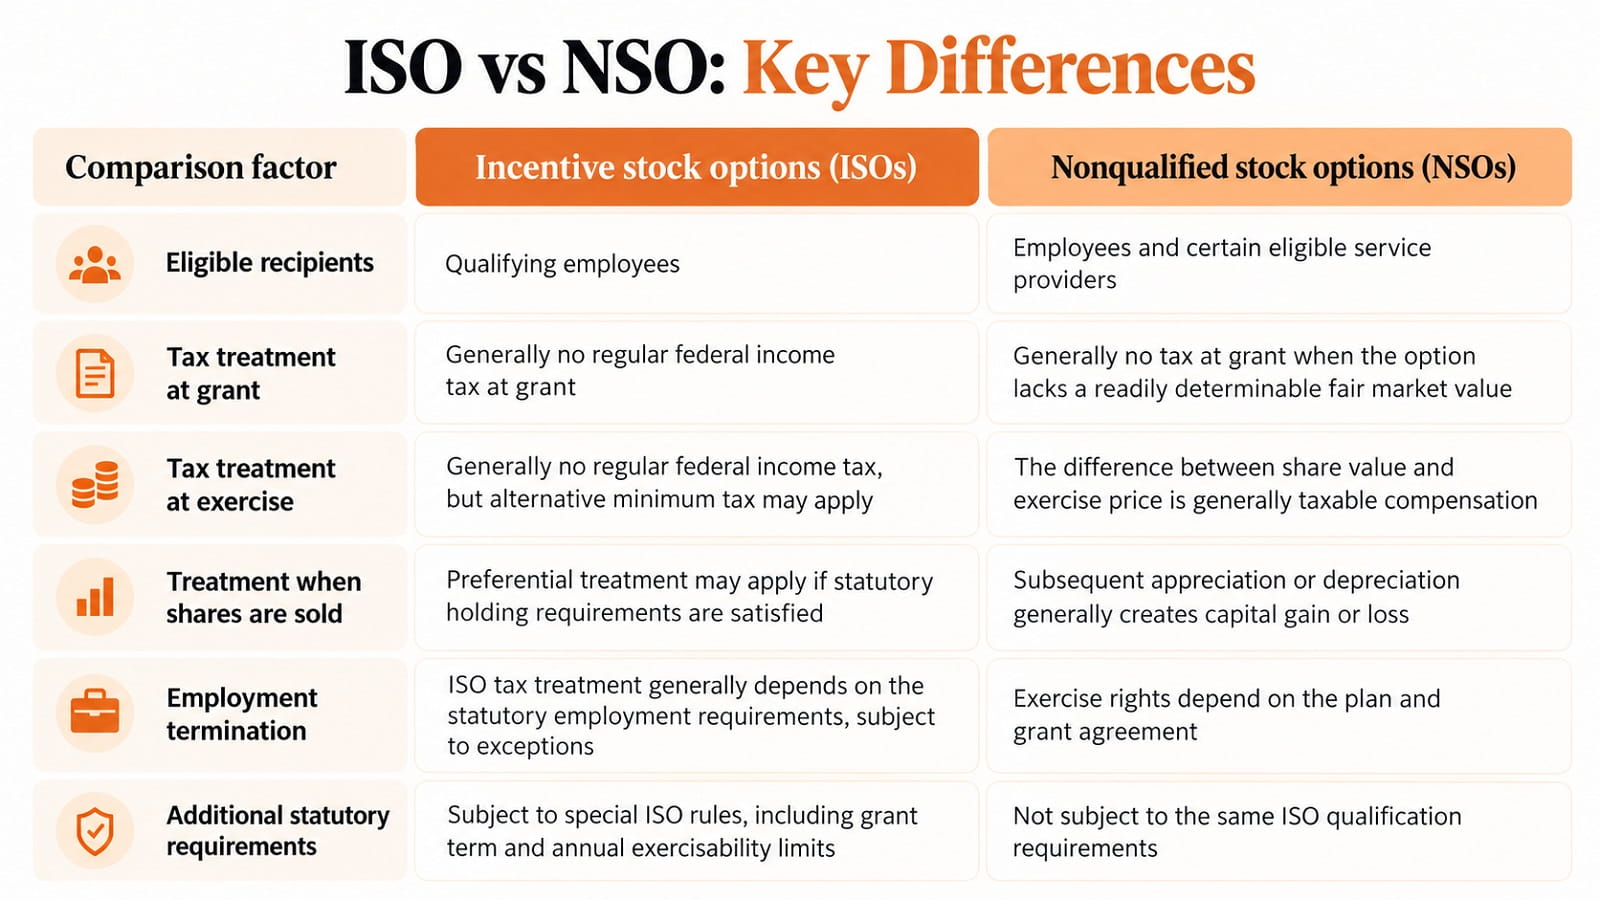
The table does not mean that an ISO always produces a better financial result. Exercising ISOs can create alternative minimum tax exposure even when the employee cannot sell the resulting shares. NSOs may create ordinary compensation income at exercise, which can also be difficult to finance in a private company.
Some grants contain both types of options, while others may cease to qualify for ISO treatment under certain circumstances. Employees should verify the classification of their particular award rather than relying on a general description of the company's equity program.
Understanding the Exercise Price and 409A Valuation
The exercise price is one of the most important terms in an option agreement. It determines how much the employee must pay to purchase each underlying share and helps establish the potential economic benefit if the value of those shares later increases.
For US private companies, a valuation under Section 409A is commonly used to support the fair market value of common stock when establishing option exercise prices. A properly supported valuation can help the company comply with applicable tax rules and reduce the risk associated with issuing discounted options.
The company's common stock valuation is not necessarily the same as the price paid by investors in a financing round. Investors may purchase preferred shares with rights that ordinary common shareholders do not possess. As a result, the price of preferred shares may be higher than the independently determined fair market value of common shares.
Consider a startup that recently issued preferred stock to investors at $12 per share while its common stock has a supported fair market value of $3 per share. An employee might receive options with a $3 exercise price, but that does not mean those shares can currently be sold for $12. The difference reflects distinct security rights and valuation assumptions, not a guaranteed immediate profit.
Employees should also understand that the exercise price is generally fixed for the particular grant. A subsequent increase in the company's common share value does not normally change the original strike price, although corporate actions or formal adjustments may affect the award under its terms.
Evaluating the Size of an Employee Option Grant
The number of options offered by a company provides limited information without the corresponding capitalization figures. A grant of 12,000 options might represent a meaningful percentage of a small startup but a very small percentage of a more mature company.
A useful starting point is the fully diluted share count, which generally includes issued shares and specified potential shares, such as outstanding options and employee equity reserves. The precise definition should be confirmed because different transactions may use different capitalization assumptions.
Suppose a company has 8 million shares on its fully diluted capitalization model and offers an employee 12,000 options. Dividing 12,000 by 8 million produces an illustrative ownership percentage of 0.15%.
That percentage may change after additional financing. If the company's fully diluted capitalization increases to 10 million shares while the employee still holds 12,000 options, the grant represents approximately 0.12% of the expanded total.
The employee has not necessarily lost options, but the proportion represented by the award has decreased. This is why a grant should be evaluated using both its current percentage and the possibility of future dilution.
A Practical Example of Exercising Employee Stock Options
Consider Riverton Labs, a fictional private software company that grants an employee 12,000 stock options with an exercise price of $3 per share. The award follows a conventional four year service arrangement with monthly vesting after a one year cliff.
After completing two years of qualifying service, the employee has 6,000 vested options. The remaining options have not yet vested, and the employee is considering whether to exercise some or all of the vested portion.
For illustration, assume the common shares have a fair market value of $8 each at the exercise date. The difference between the assumed share value and the exercise price is $5 per share.
The following table compares different partial exercise decisions. It shows the immediate purchase cost and the gross difference between the assumed fair market value and the exercise cost, before taxes, fees, and any resale restrictions.
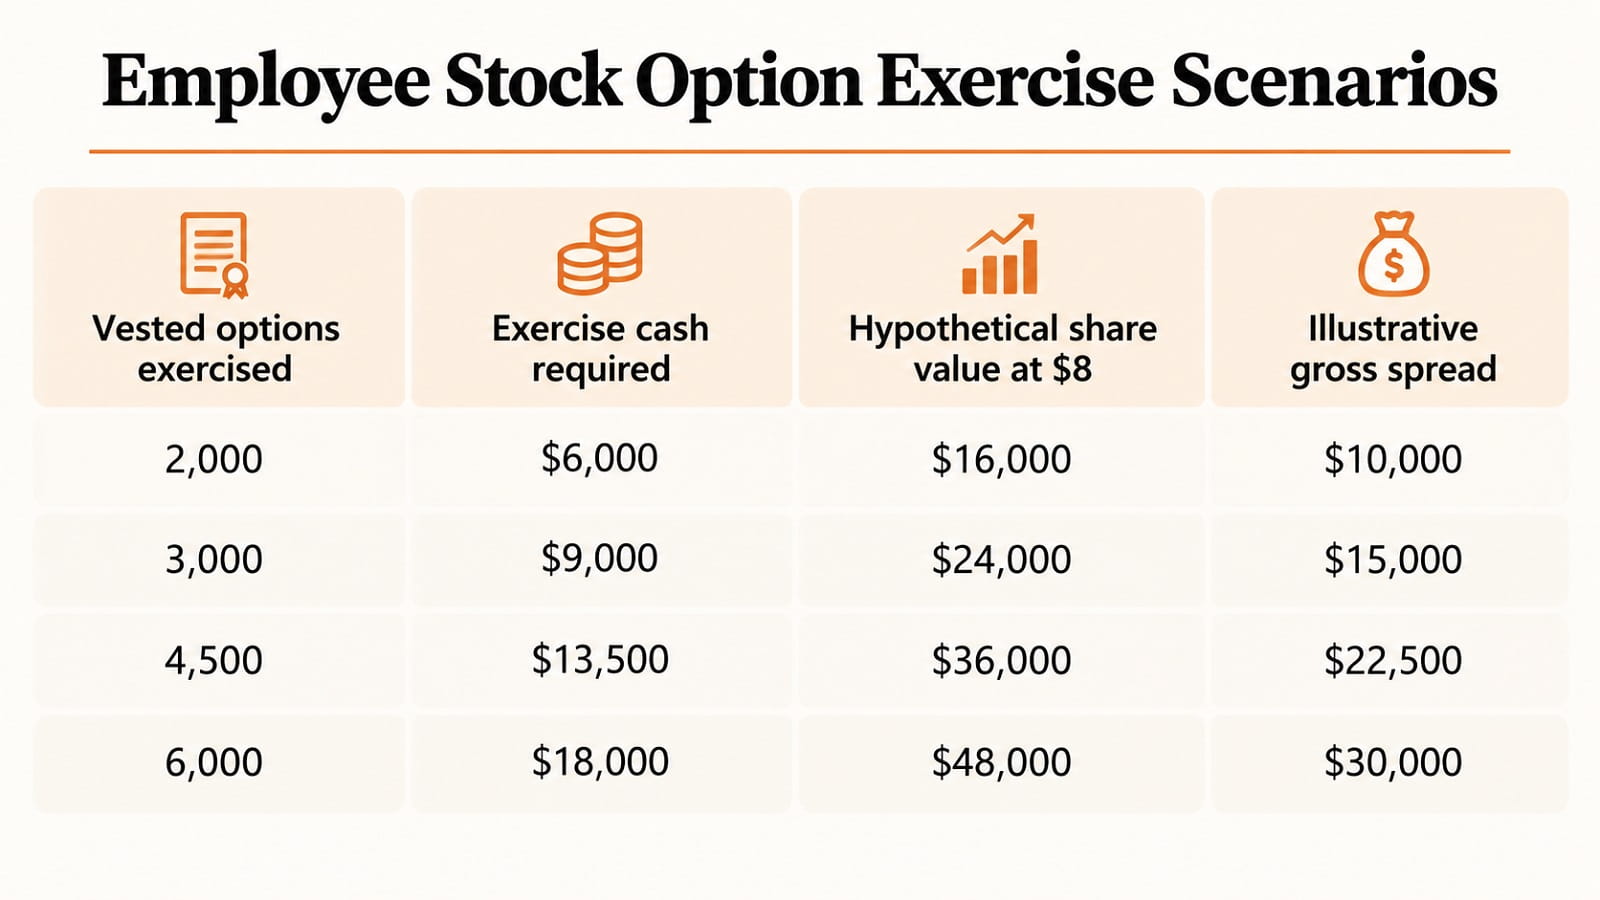
The calculations assume an exercise price of $3 for every option. Exercising 3,000 options requires $9,000, while the hypothetical value of the acquired shares would be $24,000. The resulting $15,000 difference represents the illustrative gross spread rather than guaranteed cash proceeds.
The full exercise of 6,000 vested options would require $18,000. Even though the shares are assumed to have a fair market value of $48,000 at that moment, the employee may be unable to sell them because Riverton Labs remains private.
Tax treatment also changes the practical outcome. If these are ordinary NSOs, the spread may generally create taxable compensation income at exercise. If they are ISOs, alternative minimum tax may become relevant under US rules.
The employee should therefore evaluate the exercise cost and tax consequences together. Spending $18,000 to acquire private company shares represents a different financial commitment from receiving $18,000 in salary.
Exercising Options Before They Vest
Some startups permit employees to exercise options before the usual service requirements have been completed. This arrangement is commonly known as early exercise and must be specifically authorized by the relevant equity documents.
Early exercise can allow an employee to acquire shares while their fair market value is still relatively low. However, the acquired shares may remain subject to vesting related repurchase provisions. Leaving the company before completing the applicable service period can therefore affect how many shares the employee keeps.
For certain US tax situations involving an actual transfer of restricted property, an employee may consider whether a Section 83(b) election is available and appropriate. When applicable, the election generally must be filed within 30 days after the property transfer.
An ordinary unexercised stock option does not itself qualify for that election. The relevant analysis arises when actual property has been transferred under an arrangement that satisfies the applicable requirements.
Early exercise can also increase financial exposure. An employee may spend money acquiring restricted shares before knowing whether the company will succeed or whether any opportunity to sell will become available. The decision should be evaluated with professional tax and legal advice rather than assuming that early exercise is automatically advantageous.
Tax Consequences of Exercising Stock Options
Tax treatment can have a substantial impact on the economic value of an employee option grant. In the United States, the consequences depend on whether the award is an ISO or NSO, when the options are exercised, and how the resulting shares are eventually disposed of.
For ordinary NSOs without a readily determinable fair market value at grant, the difference between the fair market value of the acquired shares and the exercise price is generally recognized as compensation income upon exercise. Later changes in share value can create capital gains or losses when the shares are sold.
ISOs receive different treatment when the statutory requirements are satisfied. Exercising an ISO generally does not create regular federal income tax at exercise, but the difference between the exercise price and fair market value may affect the alternative minimum tax calculation.
A qualifying ISO disposition generally requires that the shares are not sold within two years after the grant date or within one year after the shares were transferred through exercise. Selling earlier can result in a disqualifying disposition with different tax consequences.
US law also includes a $100,000 annual limit based on the grant date fair market value of shares for which ISOs first become exercisable during a calendar year. The portion exceeding the statutory limit is treated as nonstatutory options for federal tax purposes.
These rules are not universal across countries. Employees working internationally may face different treatment based on residence, employment location, company structure, and applicable tax treaties. A financial decision involving a substantial exercise payment should be reviewed with a qualified adviser familiar with the specific circumstances.
What Happens to Options When an Employee Leaves
Leaving a startup can substantially change the rights attached to an employee's options. Unvested options are generally forfeited under ordinary service based awards unless the agreement provides otherwise. Vested options may remain exercisable, but only within the applicable deadlines.
Many startup grants have historically used a post termination exercise period of approximately 90 days. Other companies provide longer periods, and certain termination events may receive different treatment. The actual deadline must be taken from the equity plan and individual grant documents.
The deadline for exercising an option is separate from the requirements for retaining favorable ISO tax treatment. Under general US rules, the statutory employment conditions for ISOs ordinarily require exercise within three months after qualifying employment ends, subject to exceptions.
An agreement may permit exercise after that period while the option no longer qualifies for ISO treatment. Employees should not assume that a longer contractual exercise window preserves the original tax classification.
The financial decision can be difficult when the company is private. An employee may need to pay an exercise price and potentially related taxes without knowing when the shares can be sold or whether their eventual value will exceed the purchase cost.
Before leaving, employees should confirm the number of vested options, remaining exercise period, total exercise cost, potential tax obligations, and any restrictions affecting the acquired shares.
The Role of Liquidity in Employee Stock Option Value
Private startup shares are generally less liquid than shares traded on a public exchange. An employee may exercise options and become a shareholder while having no practical opportunity to sell those shares for several years.
An acquisition may provide a liquidity event, but the amount available to common shareholders depends on the transaction terms and the company's capital structure. Preferred shareholders may have contractual rights that influence how sale proceeds are distributed.
For example, a company may be acquired at a headline valuation that appears attractive compared with earlier financing rounds. However, debt obligations, transaction expenses, and preferred shareholder liquidation preferences may reduce the amount ultimately available to common shareholders.
An initial public offering can create a publicly traded market, although employees may still be subject to lockup arrangements or other restrictions. Becoming publicly listed therefore does not necessarily mean every employee can sell shares immediately.
Secondary transactions can sometimes provide earlier liquidity, but they may require company approval and access to an eligible buyer. Employees should not assume that a privately quoted valuation establishes an available sale price.
The value of an option must therefore be considered alongside the probability, timing, and terms of a future liquidity event. An attractive theoretical spread is not equivalent to cash that the employee can currently access.
Comparing Stock Options With Other Startup Benefits
Stock options are only one component of an employment agreement. Employees may also receive salary, annual bonuses, health benefits, retirement contributions, or other forms of compensation that have more predictable current value.
A smaller salary accompanied by a substantial option grant can appear appealing when a company describes its expected future growth. However, the employee assumes the possibility that the options will never create realizable value.
A useful comparison considers the amount of guaranteed compensation being exchanged for the potential equity benefit. Employees should also consider the cash required to exercise options, the tax consequences of doing so, and whether the resulting shares can be sold.
The company's financial condition matters as well. An employee may receive a larger option percentage at a business facing significant financing uncertainty than at one with stable revenue and established customers. Neither arrangement is automatically superior, but the underlying risks differ.
For employees, the objective should be to understand the total compensation package rather than treating the stated number of options as a substitute for cash income.
How Startups Manage Employee Stock Option Grants
For founders, granting employee options requires an organized equity incentive plan and an accurate record of available shares. The company must determine which employees are eligible, obtain the necessary approvals, and document each award correctly.
A share reserve is commonly used to provide capacity for future grants. When options are granted from an existing reserve, the number of unallocated shares decreases. The company's fully diluted share count may remain unchanged if the granted options were already accounted for within that reserve.
Companies should also establish an appropriate common stock valuation process, approve exercise prices consistently, and maintain reliable records of grants, vesting, exercise, expiration, and cancellation.
US securities law can be relevant to the issuance of compensatory equity. SEC Rule 701 provides an exemption for certain qualifying securities transactions involving employees and other eligible service providers, subject to specific conditions and disclosure requirements.
A clear administration process benefits employees and founders alike. Employees can understand what they have received, while management can monitor equity commitments and prepare more reliable capitalization information for future investors.
Assessing an Employee Stock Option Offer
Before accepting an option grant, an employee should understand the number of options offered, the exercise price, the type of award, and the fully diluted capitalization used to calculate the stated ownership percentage.
The grant agreement should also explain when options become exercisable, when they expire, what happens after employment ends, and whether early exercise is permitted. Employees should verify the relevant class of shares and understand whether existing investor rights may influence future proceeds.
Where possible, the employee should ask how the company determines the fair market value of its common stock and whether any opportunities for selling shares have previously been available. The answers can help clarify the difference between an estimated valuation and practical liquidity.
An informed decision does not require predicting the company's eventual sale price. It requires recognizing the contractual rights, financial commitments, and uncertainty involved in exercising options.
Final Thoughts
Employee stock options allow startup employees to participate in potential future business value, but the opportunity comes with contractual and financial conditions. The number of options granted is only a starting point. Their usefulness depends on exercise prices, vesting requirements, tax treatment, ownership changes, and the possibility of selling the underlying shares.
The Riverton Labs example shows why employees should distinguish the cost of exercising options from the theoretical value of the shares acquired. A positive gross spread can indicate potential economic value while still requiring a meaningful cash payment and creating tax or liquidity risks.
For employees, understanding these details supports better decisions about job offers, exercise timing, and personal finances. For founders, accurate equity administration and clear grant documentation help establish a compensation program that employees can evaluate with realistic expectations.
FAQ
What Are Employee Stock Options?
Employee stock options are contractual rights that allow employees to purchase a specified number of company shares at an agreed price. They generally do not represent immediate share ownership and must be exercised to acquire the underlying shares.
Do Employees Get Stock Options for Free?
Employees generally do not pay to receive a conventional option grant. However, exercising the options usually requires purchasing the shares at the agreed exercise price, and taxes or other costs may apply.
What Is the Difference Between ISOs and NSOs?
ISOs are statutory options available to qualifying employees under US tax rules, while NSOs are nonstatutory options that may also be granted to certain eligible service providers. Their tax treatment and qualification requirements differ.
How Is an Employee Stock Option Grant Valued?
Employees can examine the number of options, strike price, applicable fully diluted share count, and fair market value of the underlying shares. Actual financial proceeds also depend on taxes, restrictions, and the opportunity to sell the shares.
Can Employees Exercise Options Before They Vest?
Some grants permit early exercise, but the right must be included in the applicable documents. Shares acquired through early exercise may remain subject to repurchase or other restrictions.
What Happens if the Share Price Falls Below the Exercise Price?
Options with an exercise price above the current share value have no positive intrinsic spread at that price. An employee may choose not to exercise, although the options could regain value before expiration if circumstances change.
Do Employees Pay Taxes When They Exercise Options?
They may. NSOs generally create taxable compensation at exercise when the underlying shares are worth more than the exercise price. ISOs may create alternative minimum tax exposure even when regular federal income tax does not arise at exercise.
Can Employees Sell Shares Immediately After Exercising?
Not necessarily. Private company shares may be subject to transfer restrictions, and a willing buyer may not be available. A permitted secondary sale, acquisition, or public listing may eventually provide liquidity.
What Happens to Stock Options After Leaving a Company?
Unvested options are generally forfeited under standard arrangements, while vested options may remain exercisable for a defined period. The employee should check the grant agreement and consider the applicable tax rules before exercising.
Can Employee Stock Options Become Worthless?
Yes. Options may expire without positive economic value, the company may lose value, or the employee may be unable to complete an exercise before the deadline. A grant does not guarantee future financial returns.

Mobina Khanki
Venture & Funding Writer at PinerookMobina Khanki covers venture capital, startup funding, fundraising, and startup finance for Pinerook, focusing on founders and investors.
 Seen first.


